NPS Vatsalya is a PFRDA-regulated contributory savings scheme created specifically for minor children. The account is opened in the minor’s name, while the parent or legal guardian operates it until the child reaches majority. The scheme was launched on 18 September 2024 and its framework was subsequently updated through the NPS Vatsalya Scheme Guidelines 2025, issued by PFRDA in January 2026.
The current PFRDA information states that an eligible minor can start with ₹250 at account opening and ₹250 in each financial year, with no maximum contribution limit. Returns are market-linked rather than a fixed interest rate, so the final corpus depends on contributions, investment allocation and market performance.
Desk4Info readers can also follow our Government Schemes section for other verified government financial schemes and citizen-benefit updates.
NPS Vatsalya 2026: Key Details
| Detail | Verified Information |
|---|---|
| Scheme | NPS Vatsalya |
| Regulator | Pension Fund Regulatory and Development Authority (PFRDA) |
| Eligible Subscriber | Indian citizen below 18 years; eligible NRI/OCI minors are also covered |
| Account Operator | Parent or legal guardian |
| Minimum Opening Contribution | ₹250 |
| Minimum Annual Contribution | ₹250 |
| Maximum Contribution | No maximum limit |
| Returns | Market-linked; not a fixed or guaranteed interest rate |
| Regulatory Authority | PFRDA Official Website |
Eligibility, Contribution and Investment Rules
NPS Vatsalya is available for an Indian citizen below 18 years of age. The current PFRDA framework also covers eligible NRI and OCI minors. The minor remains the sole beneficiary, while the guardian manages the account until majority.
The contribution structure has an important current update. The 2025 guidelines prescribe ₹250 minimum initial and annual contribution, while subsequent contributions can be as low as ₹10 under the operational contribution framework. There is no maximum contribution ceiling, and relatives or friends may also contribute for the minor.
Investment returns are not guaranteed. The guardian can select a PFRDA-registered Pension Fund, and the money is invested according to the applicable investment framework.
⚠️ Critical Mandatory Warning: NPS Vatsalya is a market-linked investment product, not a fixed-interest deposit. Past or assumed returns should not be presented as guaranteed future returns.
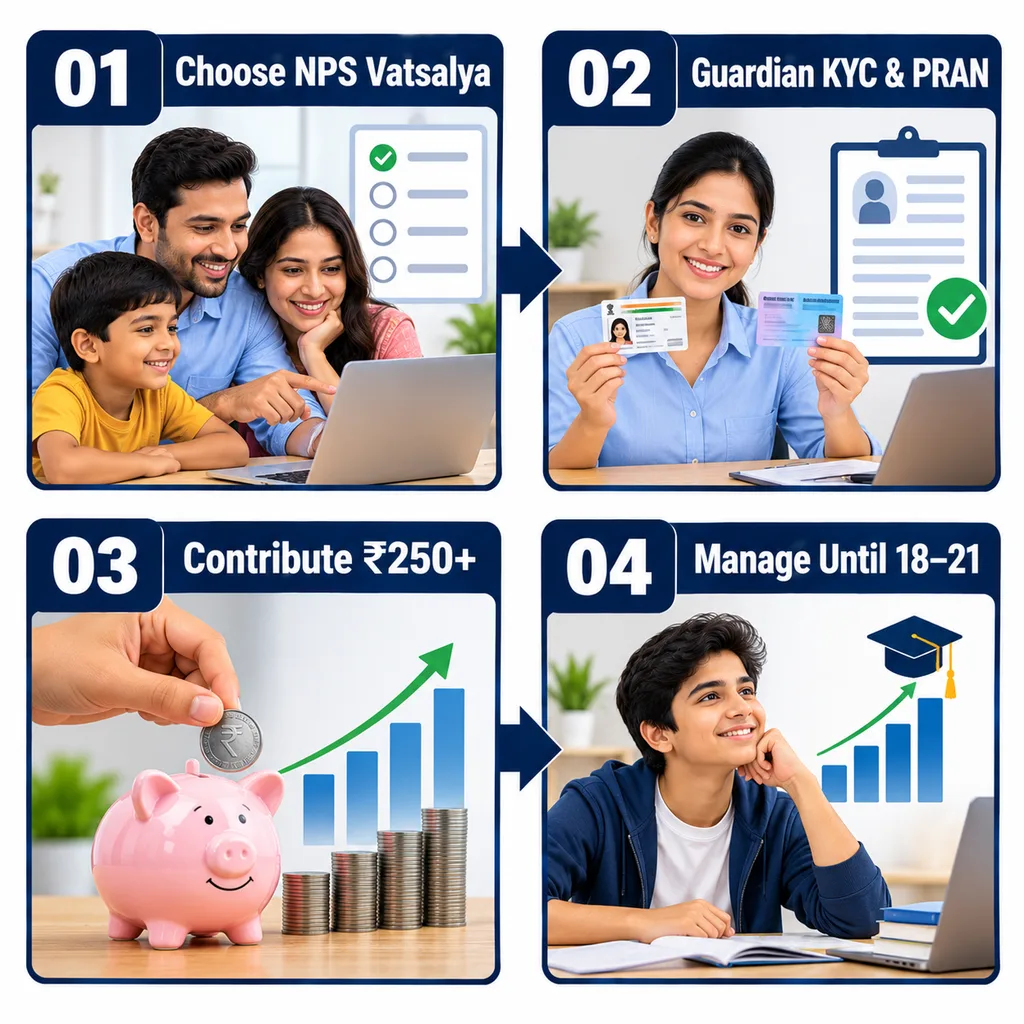
Gateway Management: Account Opening, PRAN and Withdrawals
NPS Vatsalya account registered Points of Presence, online facilities and the eNPS route se open kiya ja sakta hai. Account minor ke naam par hota hai aur PRAN usi minor subscriber ke naam se generate hota hai. Resident minor ke liye opening stage par bank account details optional ho sakti hain, jabki NRI/OCI cases mein applicable bank documentation required hoti hai.
Partial withdrawal immediately available nahi hota. Account opening ke 3 years complete hone ke baad specified purposes—education, specified medical treatment aur specified disability—ke liye own contributions, returns ko exclude karke, maximum 25% tak withdrawal permitted hai. Current PFRDA rules pre-18 period mein maximum two withdrawals aur 18–21 period mein additional two withdrawals provide karte hain, subject to applicable conditions.
18 Saal Ke Baad Kya Hoga?
Child ke 18 saal complete hone par fresh KYC aur nominee details update karna mandatory hai. Is stage par subscriber NPS Vatsalya ko 21 years tak continue kar sakta hai, accumulated corpus ko applicable NPS model mein shift kar sakta hai, ya prescribed exit provisions ke according account close kar sakta hai.
Agar exit choose kiya jata hai aur corpus ₹8 lakh se kam hai, entire corpus lump sum mein withdraw kiya ja sakta hai. Corpus ₹8 lakh ya usse zyada hone par up to 80% lump sum withdrawal aur at least 20% annuity purchase ke liye use karna applicable rule hai.
Agar subscriber 18 se 21 ke beech koi option exercise nahi karta, current PFRDA framework ke according account same Pension Fund ke higher-equity scheme mein automatically shift ho sakta hai, after which applicable NPS exit regulations govern the account.
Tax Benefit and Important Financial Caveat
Current PFRDA information states that eligible parent/guardian contributions can receive a deduction of up to ₹50,000 under the applicable provision corresponding to Section 80CCD(1B), subject to the applicable tax regime and statutory conditions. The current PFRDA page also describes tax treatment for qualifying partial withdrawals and exit proceeds.
Tax rules can change through Finance Acts and annual notifications. Therefore, taxpayers should verify the applicable assessment year provisions before claiming any deduction.
Red-Flag Mistakes Before Opening an Account
- Minor ki DOB proof mein mismatch: Birth certificate, school-leaving certificate, matriculation certificate, PAN or passport, as applicable, should contain consistent details.
- Guardian KYC incomplete: Aadhaar or another accepted KYC document plus PAN/Form 60 may be required.
- ₹250 annual minimum ko ignore karna: Current framework mein annual minimum contribution requirement applicable hai.
- Guaranteed return samajhna: NPS Vatsalya market-linked hai.
- 18-year transition miss karna: Majority par fresh KYC aur nominee details update karna important hai.
- Withdrawal ko normal savings account samajhna: Partial withdrawal specified purposes aur prescribed conditions ke subject mein hai.
NPS Vatsalya FAQs
Kya NPS Vatsalya mein ₹250 se account open ho sakta hai?
Haan, current PFRDA framework ke according minimum opening contribution ₹250 hai. Annual minimum contribution bhi ₹250 hai.
Kya NPS Vatsalya mein guaranteed interest milta hai?
Nahi, NPS Vatsalya ka return fixed interest rate ke roop mein guaranteed nahi hai. Contributions market-linked investments mein lagti hain aur returns Pension Fund ke performance par depend karte hain.
Bachcha 18 saal ka hone par account ka kya hota hai?
18 saal par fresh KYC aur nominee details complete karni hoti hain. Subscriber prescribed rules ke according account ko 21 years tak continue, NPS mein shift ya exit kar sakta hai.
Official Departmental Directory
| Purpose | Official Resource |
|---|---|
| NPS Vatsalya Scheme Details | PFRDA NPS Vatsalya Page |
| Account Opening | Open NPS Vatsalya |
| NPS Vatsalya Guidelines | 2025 Scheme Guidelines PDF |
| Latest FAQs | PFRDA NPS Vatsalya FAQs |
| Regulator | PFRDA Official Website |
| NPS Trust | NPS Trust Official Website |
Editorial Integrity Disclaimer
NPS Vatsalya ke contribution, withdrawal, taxation, investment aur exit provisions regulatory updates ke subject hain. PFRDA ne 16 June 2026 ko updated NPS Vatsalya FAQs publish kiye hain, isliye account open karne ya financial/tax decision lene se pehle latest PFRDA Official Website aur NPS Trust material ko verify karein.
Source note: Current PFRDA page and 2025 Scheme Guidelines were used as the primary regulatory sources; the latest FAQ available on PFRDA is dated 16 June 2026.