Post Office Monthly Income Scheme, officially known as the National Savings (Monthly Income Account) Scheme, 2019, is a government small-savings product designed to provide regular monthly interest income. The scheme is administered through the Department of Posts, while the interest rates on small-savings instruments are notified for quarterly periods by the Government.
For the current July–September 2026 quarter, the National Savings Institute lists the MIS interest rate at 7.4% per annum. The official rate table shows 7.4% across all four quarters of FY 2026–27 in its currently published schedule, although future government notifications can change rates.
The account requires a minimum deposit of ₹1,000, with deposits made in multiples of ₹1,000. The maximum permitted investment is ₹9 lakh in a single account and ₹15 lakh in a joint account. These higher ceilings were introduced through the 2023 amendment to the MIS rules.
For readers comparing government-backed savings products, the Finance & Market section can be used alongside official scheme documents before making an investment decision.
Post Office MIS 2026 — Key Details
| Particular | Current Information |
|---|---|
| Scheme Name | National Savings (Monthly Income Account) Scheme, 2019 |
| Popular Name | Post Office Monthly Income Scheme (MIS) |
| Current Interest Rate | 7.4% per annum |
| Interest Payment | Monthly |
| Minimum Deposit | ₹1,000 |
| Single Account Maximum | ₹9 lakh |
| Joint Account Maximum | ₹15 lakh |
| Tenure | 5 years |
| Premature Closure | Allowed after 1 year, subject to applicable deduction |
| Account Opening | Post Office and eligible digital channels |
Eligibility and Maximum Investment Rules
MIS accounts can be opened by a single adult or jointly by up to three adults. A guardian can open an account on behalf of a minor or an authorised person, while a minor who has attained 10 years can also open and operate an account in their own name under the scheme rules.
An individual may hold more than one MIS account, but the applicable investment ceiling has to be respected. The 2023 amendment increased the ceiling from ₹4.5 lakh to ₹9 lakh for a single account and from ₹9 lakh to ₹15 lakh for a joint account.
The important point is that the maximum limit is not simply a per-account figure that can be multiplied indefinitely. Deposits held by an individual across applicable MIS holdings have to remain within the prescribed ceiling, with the depositor’s share in joint holdings considered according to the rules.
⚠️ Critical Mandatory Warning: ₹9 lakh and ₹15 lakh are the prescribed overall investment ceilings for single and joint MIS categories. Multiple accounts cannot be used to bypass the applicable limit.
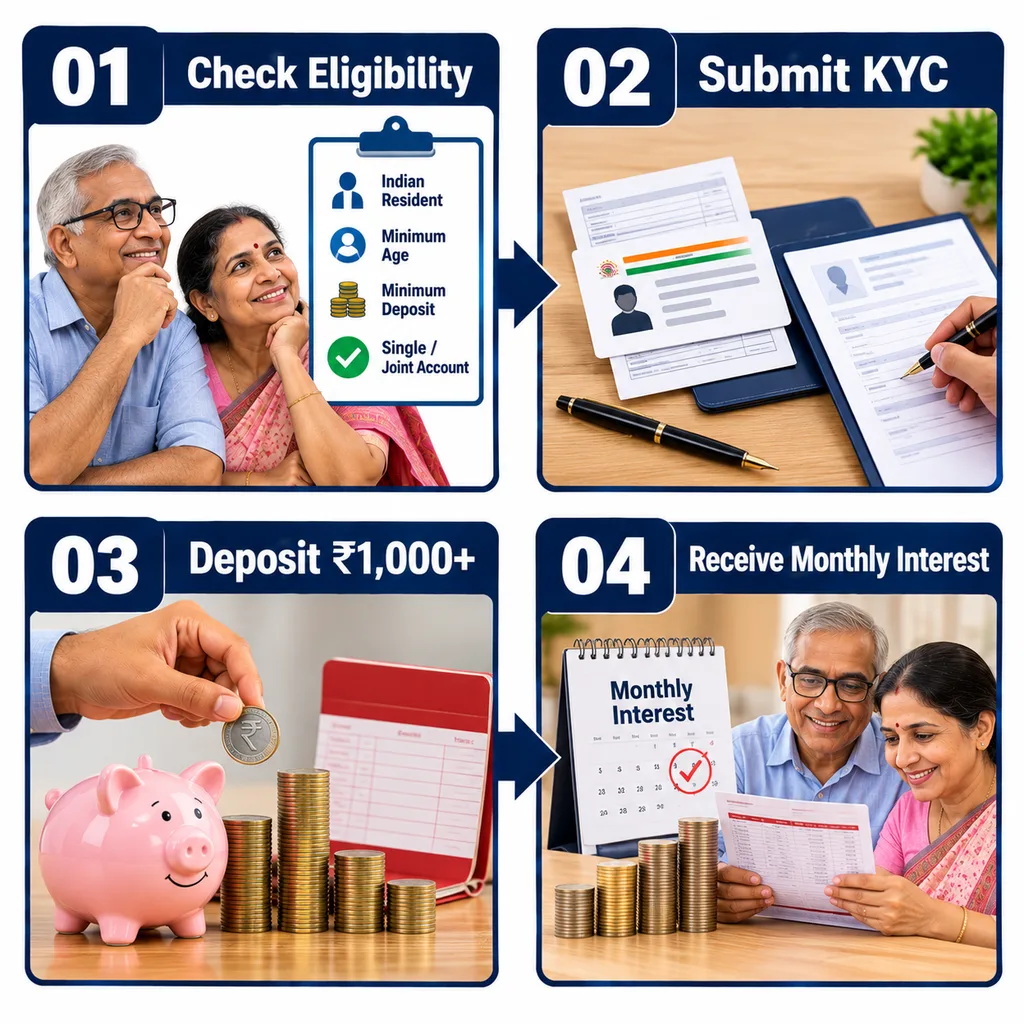
Gateway Management: Account Opening and Monthly Interest
India Post ke current customer material ke according MIS account Post Offices mein open kiya ja sakta hai. Standard documentation includes two passport-size photographs, Aadhaar and PAN, with Form 60 available where PAN is not furnished, subject to applicable KYC rules.
India Post ne digital access bhi expand kiya hai. MIS account opening facility DOP Internet Banking mein 20 October 2023 se available hai for eligible Post Office Savings Account customers. Official workflow mein login ke baad General Services → Service Requests → New Requests → MIS Accounts – Open a MIS Account select karke deposit amount aur linked savings account choose karna hota hai.
2025 mein Aadhaar-based e-KYC facility ko individual adult MIS account opening ke liye departmental post offices mein extend kiya gaya. Isse eligible customers ke onboarding process mein Aadhaar authentication ka additional digital route available hua.
Monthly interest account opening ke ek month complete hone ke baad payable hota hai. It can be credited to a Post Office Savings Account or transferred through applicable electronic mechanisms to the depositor’s bank account.
₹9 Lakh MIS Par Monthly Income Kitni?
At the current 7.4% annual rate, a ₹9 lakh single-account deposit gives an annual interest calculation of ₹66,600.
Monthly equivalent:
₹66,600 ÷ 12 = ₹5,550 per month
Similarly, a ₹15 lakh joint-account deposit at 7.4% gives:
₹15,00,000 × 7.4% = ₹1,11,000 per year
Monthly equivalent:
₹1,11,000 ÷ 12 = ₹9,250 per month
These are simple calculations based on the currently published 7.4% rate. They should not be interpreted as a guaranteed rate for future quarters, because small-savings rates are subject to government notification.
The scheme pays interest monthly; however, if the monthly interest is not withdrawn, it does not itself earn additional interest under the MIS account.
Premature Closure and 5-Year Maturity
MIS has a 5-year maturity period. The account cannot normally be closed before one year from the date of opening.
If the account is closed after one year but before completion of three years, an amount equal to 2% of the deposit is deducted. Where premature closure occurs after three years but before maturity, the deduction is 1% of the deposit.
For example, if a ₹9 lakh account is closed after two years under the applicable premature-closure rule, the 2% deduction would be ₹18,000 from the deposit amount, subject to the actual scheme rules applicable to the account.
After five years, the account reaches maturity and the deposit can be claimed according to the applicable rules.
There is no need to confuse MIS with a recurring-deposit product: the scheme is structured around one deposit at account opening, with monthly interest thereafter.
Tax Treatment and KYC Considerations
MIS interest is investment income and should not be treated as tax-free merely because the account is operated through a government Post Office. Tax treatment depends on the taxpayer’s applicable provisions and tax regime.
For senior citizens, the Income Tax Department states that Section 80TTB can provide a deduction of up to ₹50,000 on eligible interest from deposits with banks, Post Office or cooperative banks, subject to the statutory conditions. The Department also states that the applicable TDS threshold for senior citizens under Section 194A is ₹50,000.
Tax rules have also undergone legislative changes from 1 April 2026, so an article should not blindly reproduce older TDS section references. The Income Tax Department says payments or credits on or after 1 April 2026 are governed by the corresponding provisions of the Income Tax Act, 2025.
For an individual investor, the practical approach is simple: retain interest statements, review AIS/Form 26AS where applicable, and report taxable interest according to the applicable tax provisions.
Red-Flag Mistakes Before Opening MIS
- Exceeding the ₹9 lakh single-account ceiling through multiple accounts.
- Treating 7.4% as permanently guaranteed: the rate is subject to government notifications.
- Expecting premature closure within one year: this is not normally permitted.
- Ignoring the 1% or 2% premature-closure deduction applicable according to the closure period.
- Assuming unpaid monthly interest compounds: MIS interest does not earn additional interest merely because it remains unclaimed.
- Using outdated KYC information: current India Post processes include Aadhaar-based e-KYC for eligible individual adult MIS onboarding.
- Ignoring taxation: government-backed does not automatically mean tax-free.
Post Office MIS FAQs
Can I open more than one MIS account?
Yes, an individual may open more than one account subject to the applicable overall investment ceiling. The combined holding cannot be used to exceed the prescribed ₹9 lakh single-account category limit or applicable joint-account ceiling.
Can MIS be closed before five years?
Yes, but normally not before completion of one year from opening. Closure between one and three years attracts a 2% deduction, while closure after three years but before maturity attracts a 1% deduction.
Can a 10-year-old minor operate an MIS account?
Yes, the scheme permits a minor who has attained 10 years to open and operate an account in their own name. A guardian can also open an MIS account on behalf of a minor.
Official Departmental Directory
| Purpose | Official Resource |
|---|---|
| India Post Main Portal | India Post Official Website |
| Post Office Savings Services | India Post Savings Services |
| MIS Scheme Rules | National Savings MIS Scheme Rules |
| 2023 Limit Amendment | India Post SB Order 01/2023 |
| Current Small Savings Rates | National Savings Institute |
| India Post Internet Banking | DOP eBanking Portal |
| Customer Care | India Post Contact & Customer Care |
Current India Post Helpdesk
India Post currently lists its customer-care toll-free number as 1800 266 6868. The published contact page states that call-centre agents are available from 8 AM to 8 PM, while IVRS is available 24×7 except gazetted holidays.
Editorial Integrity Disclaimer
Post Office MIS ka 7.4% rate September 2026 tak currently published rate schedule ke according verified hai. Future quarter mein interest rate change ho sakta hai, isliye investment se pehle latest National Savings Institute notification aur India Post scheme rules check karein.
Account opening, KYC, premature closure aur tax treatment ke liye current official instructions ko priority dein. India Post ke official scheme documents aur Department of Economic Affairs ke notified rules ko third-party summaries se upar maana jana chahiye.